Reading through a health insurance policy feels a lot like reading the terms and conditions of a software update written in ancient Latin. Most of us flip through the packet, see a dizzying word soup of percentages, asterisks, and five-syllable jargon, and quietly shove the paperwork into a drawer hoping our immune systems carry us through the year. It seems fine until you stub your toe badly enough to hear a snap, land in an urgent care lobby, and realize you have no idea who owes what.
Underneath all the bureaucratic camouflage, your health plan boils down to three primary knobs that control your cash flow: premiums, deductibles, and copays. Once you see how these three gears click together, picking a plan looks less like gambling on a roulette wheel and more like basic monthly budgeting.
The Premium: Your VIP Club Membership Fee
The premium is the recurring amount you pay just to keep your coverage active. Whether you visit a physician five times a week or haven’t stepped inside a clinic since the Obama administration, the premium comes out of your paycheck or bank account like clockwork.
Think of it like an all-access gym membership. You pay the fee on the first of every month. The gym doesn’t care if you spend three hours a day on the treadmill or if your only workout consists of buying a smoothie at the front desk and heading home to nap. The bill arrives regardless.
-
How it works: Typically split between paychecks if you get insurance through an employer, or billed monthly if you buy on an exchange.
-
The trap: Paying a high monthly premium guarantees you have insurance; it does not mean your doctor visits suddenly become free.
-
The trade-off: Plans with very high premiums usually feature smaller deductibles, while rock-bottom monthly premiums stick you with massive deductibles.
The Deductible: The Brick Wall Before Help Arrives
If the premium gets you through the front door, the deductible is the toll booth standing right behind it. Your deductible is the exact dollar figure you have to fork over out-of-pocket for medical care before your insurer chips in a single penny.
Suppose your plan comes with a $2,500 deductible. If you slice your hand open while trying to pit an avocado and the ER bill comes to $1,800, your insurance company will send you an Explanation of Benefits that basically says, “We reviewed your claim! You were treated! That will be $1,800, payable directly to the hospital. Have a nice day.” Until your collective medical receipts cross that $2,500 threshold, you are flying solo on most non-preventive services.
-
Preventive care exception: By law, routine annual checkups, mammograms, and standard vaccines are generally covered at no extra charge before your deductible is met, provided you stay in-network.
-
The annual reset button: Deductibles reset every plan year, usually on January 1st. If you hit your deductible on December 28th, you get about three days of financial relief before the meter drops back to zero.
The Copay: The Cover Charge at the Clinic Door
A copay (short for copayment) is a flat fee you pay on the spot for a specific medical service. When you show up at your primary care physician’s desk, hand over your insurance card, and slide across a crisp $25 or $30, that is your copay.
Copays are predictable, which makes them the least terrifying member of the insurance family. They don’t fluctuate based on whether the doctor spends five minutes or forty-five minutes examining you.
-
Primary Care Visits: Typically lowest ($20 to $40).
-
Specialists: Higher ($50 to $100), because dermatologists and cardiologists have fancier machines and longer titles.
-
Urgent Care & ER: Highest ($50 to $300+), designed to discourage people from using trauma bays for mild seasonal allergies.
-
Prescriptions: Often tiered, meaning cheap generics cost $5 to $15, while brand-name drugs demand a much stiffer copay.
(Note: Don’t confuse copays with coinsurance. Coinsurance is a percentage split—like 80/20—that kicks in after your deductible is met, whereas a copay is a fixed dollar amount.)
Quick Comparison: The “Big Three” at a Glance
| Term | What It Is | When You Pay It | Does It Go Toward Your Out-of-Pocket Max? |
| Premium | The recurring cost to stay insured | Every month, no matter what | No |
| Deductible | The initial dollar total you pay before coverage starts | As medical bills arrive during the year | Yes |
| Copay | A flat fee for an office visit or prescription | At the time of service | Yes (on almost all modern plans) |
Putting It All Together: A Real-World Disaster Scenario
To see how these pieces interact in real life, meet Dave. Dave signs up for an individual plan with the following numbers:
-
Monthly Premium: $350
-
Annual Deductible: $2,000
-
Primary Care Copay: $30
-
Coinsurance: 20% (insurance pays 80%)
-
Out-of-Pocket Maximum: $6,000
Dave pays his $350 every month. In March, he catches a nagging chest cough, visits his regular doctor, pays a $30 copay, gets an antibiotic for a $10 copay, and goes home. His deductible remains largely untouched because standard office copays bypass the deductible on his plan.
Then comes June. Dave decides to relive his teenage skateboarding glory days, promptly falls off a curb, and shatters his wrist. The emergency room, orthopedic surgeon, and titanium plate bill totals $8,000.
-
Step 1: Dave pays his $2,000 deductible out of his savings. His remaining medical bill is now $6,000 ($8,000 minus $2,000).
-
Step 2: Now that the deductible is satisfied, his coinsurance activates. The insurer covers 80%, and Dave pays 20% of the remaining $6,000, which comes out to $1,200.
-
Step 3: Dave’s total out-of-pocket hit for the wrist repair is $3,200 ($2,000 deductible + $1,200 coinsurance).
-
Step 4: For the rest of that calendar year, Dave only pays 20% for any additional covered medical care until his total spending hits his $6,000 Out-of-Pocket Maximum, at which point the insurer covers 100% of covered in-network costs.
How to Choose What Fits Your Lifestyle
Insurance companies love giving people choices because it lets them package risk in different wrappers. Choosing the right setup comes down to your personal health track record and your bank account’s emergency cushion.
When to Pick a High-Deductible, Low-Premium Plan (HDHP)
-
You are young, healthy, and your medical history consists mostly of routine dental cleanings and occasional ibuprofen.
-
You have enough money stashed in a rainy-day fund to absorb a surprise $3,000 or $5,000 hospital bill without defaulting on rent.
-
You want access to a Health Savings Account (HSA), which allows you to put pre-tax cash away for medical expenses.
When to Pick a Low-Deductible, High-Premium Plan
-
You manage a chronic illness, take regular specialty medications, or have planned surgeries on the horizon.
-
You have small children who treat urgent care waiting rooms like a secondary daycare.
-
You live paycheck-to-paycheck and would rather budget a fixed, predictable monthly expense than face an unexpected four-figure bill out of nowhere.
The Bottom Line for Your Budget
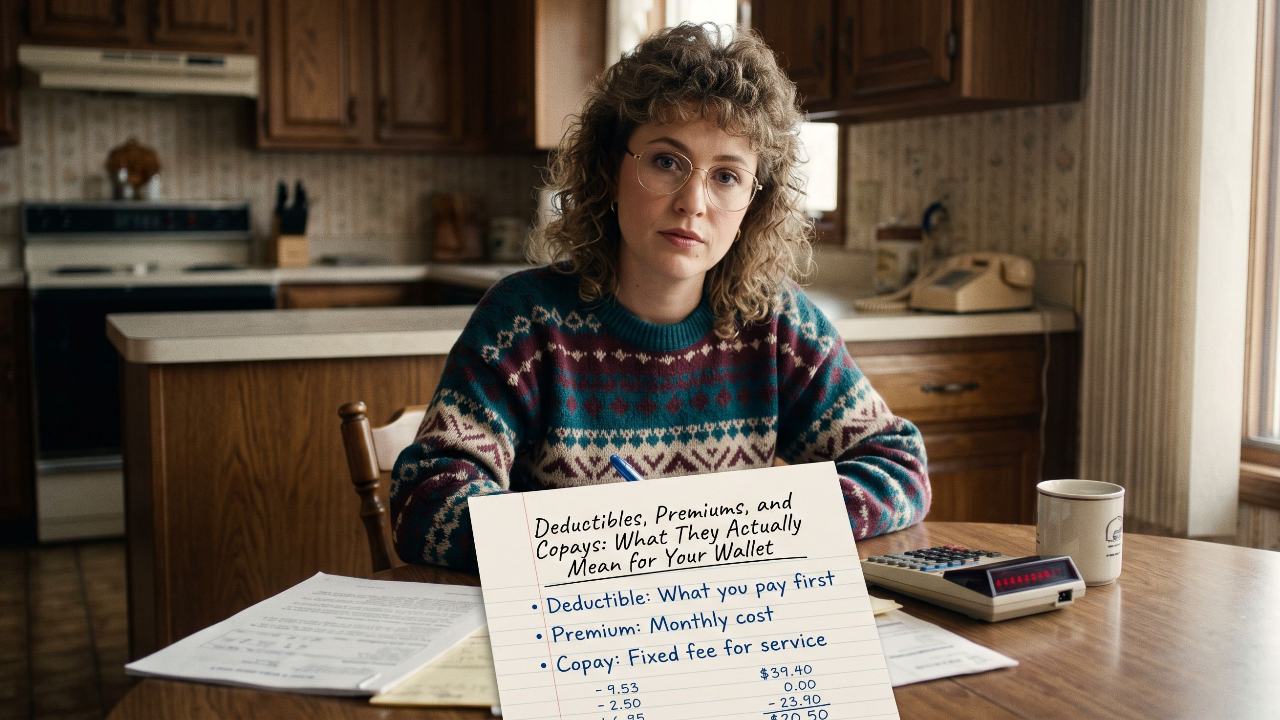
Health insurance is ultimately an expensive shield against catastrophic bankruptcy, not a golden ticket to free medical appointments. If you prioritize low monthly deductions from your salary, prepare to shoulder the financial burden if you break a bone. If you cannot stomach surprise medical invoices, accept the sting of a steeper monthly premium for peace of mind. Balancing the trade-off between what you pay today and what you might owe tomorrow is the real trick to surviving open enrollment with your sanity intact.